Risk Is a Path, Not a Number
第 1 封:風險是路徑,不是數字
Dear Shareholders,
致股東:
Vertex Macro began the year with a narrow objective: protect the ability to make the next decision. That objective sounds conservative, but it is the foundation of compounding. A portfolio that suffers an irreversible drawdown loses more than capital. It loses optionality, bargaining power, and the freedom to wait for a better price.
極點宏觀在年初設定了一個狹窄但重要的目標:保護我們繼續作出下一個決策的能力。這個目標看似保守,實際上卻是複利的基礎。當投資組合承受不可逆的回撤,失去的不只是資本,也包括選擇權、議價能力,以及等待更佳價格的自由。
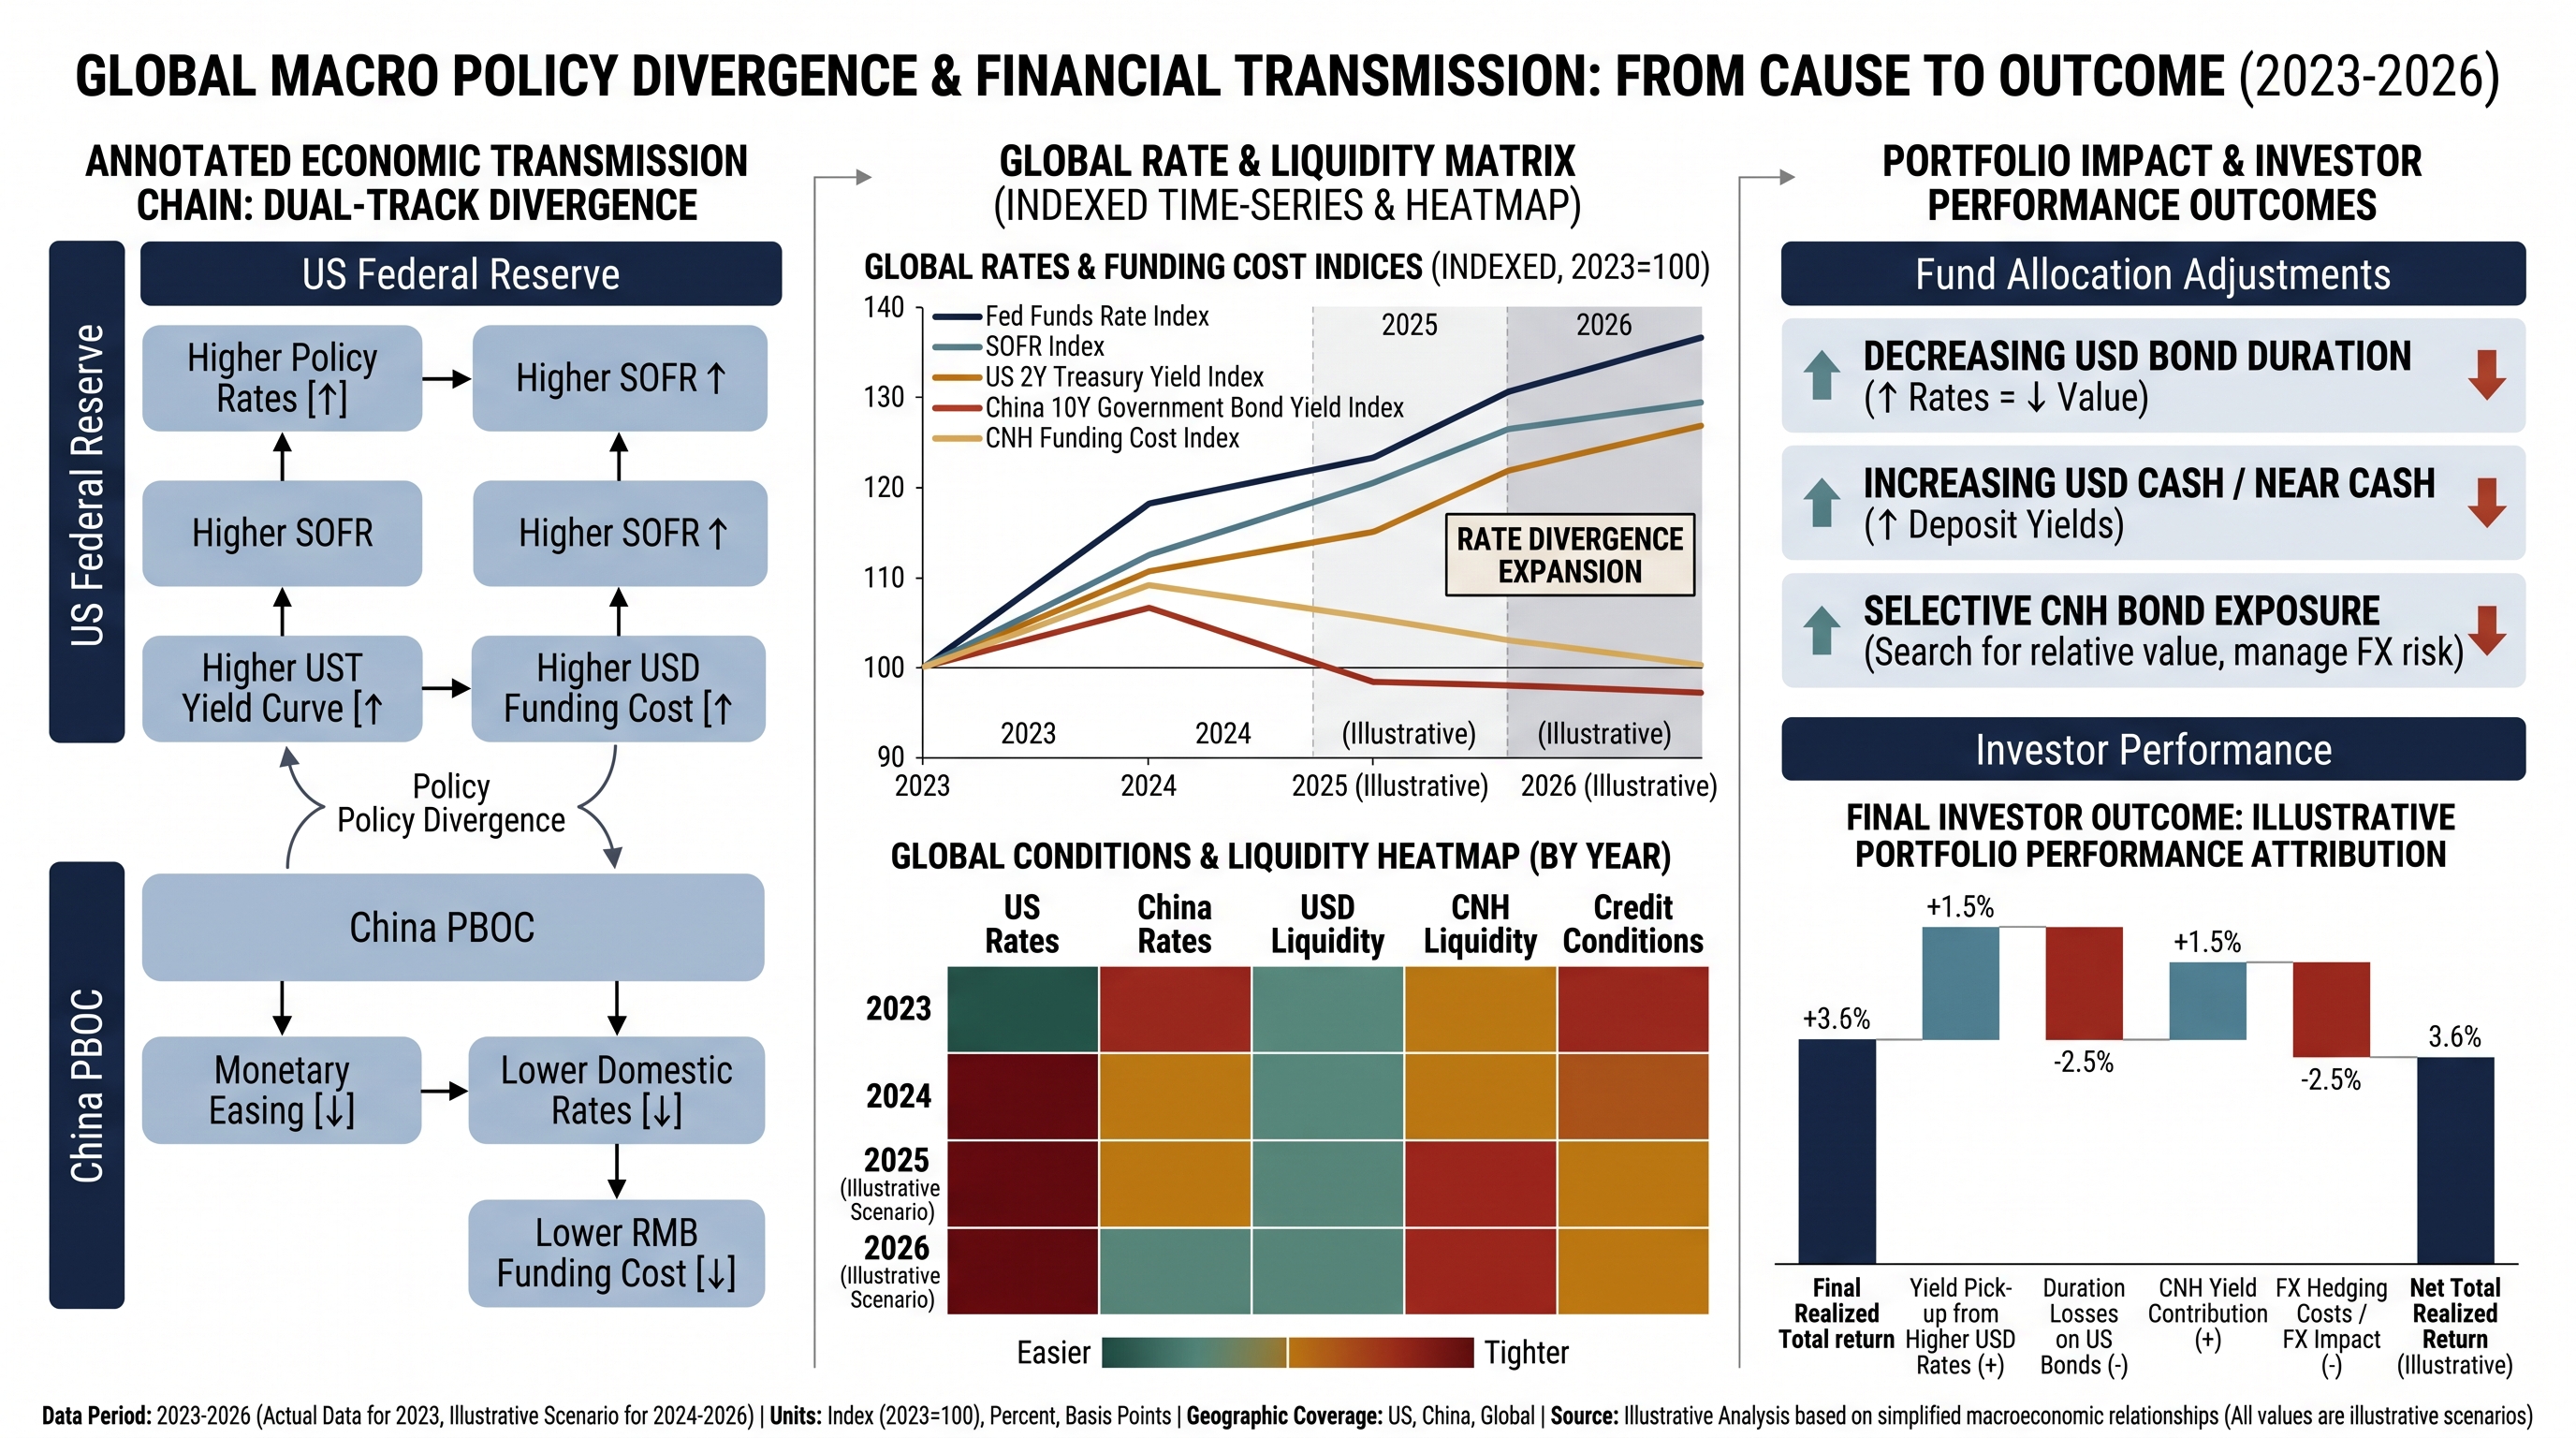
Our trading framework therefore starts with the path through which risk moves, rather than with a forecast of where an index will finish. We compress the market into a monitoring chain: energy and supply conditions influence inflation expectations; inflation expectations alter nominal and real rates; rates change funding costs and liquidity; liquidity changes cross-asset correlation; correlation determines whether a hedge remains a hedge. This is not a claim that markets are mechanically predictable. It is a method for locating the active transmission variable before it reaches portfolio P&L.
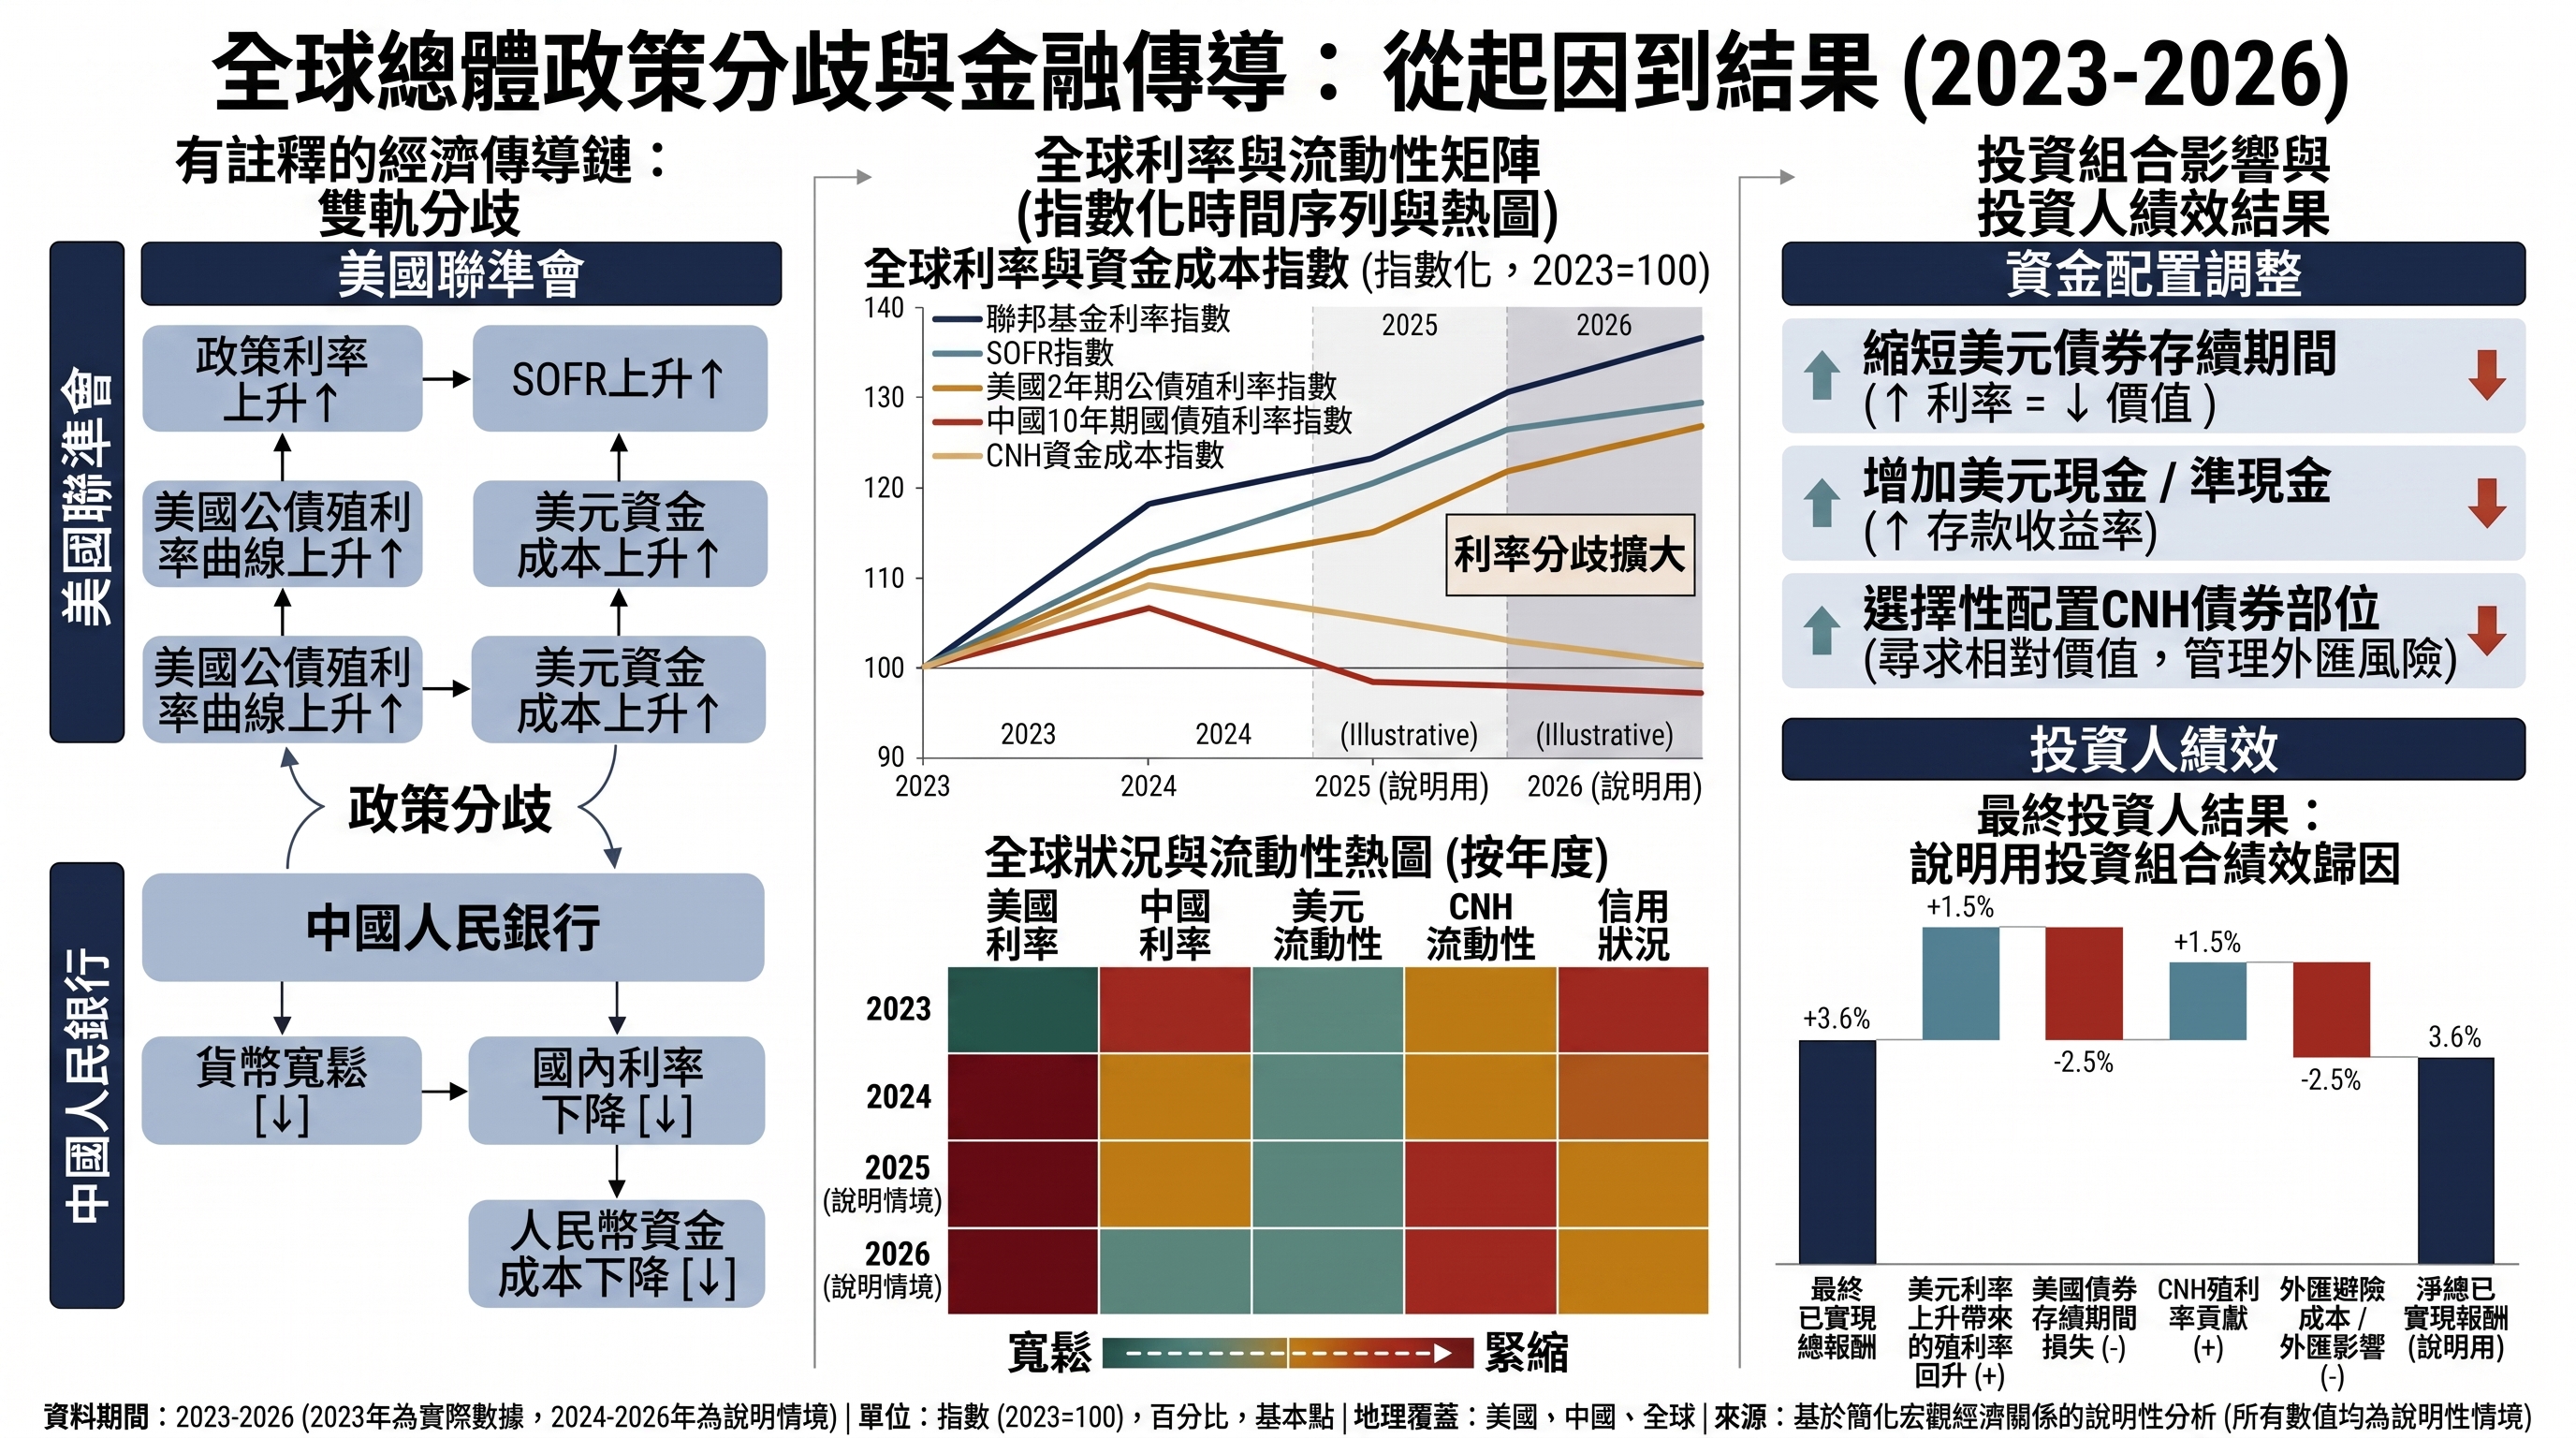
因此,我們的交易框架不是先預測某個指數年底會到哪裡,而是先理解風險如何沿著路徑傳導。我們把市場壓縮成一條監控鏈:能源與供給條件影響通膨預期,通膨預期改變名目與實質利率,利率改變融資成本與流動性,流動性改變跨資產相關性,而相關性決定原本的避險是否仍然有效。這並不是宣稱市場能被機械式預測,而是嘗試在風險進入投資組合損益之前,找出當期真正主導傳導的中介變數。
Our market thinking this month was defined by uncertainty about the quality of growth. Rising oil, rising yields, and rising equities can coexist when stronger demand and earnings revisions absorb the higher discount rate. The same three price movements become dangerous when oil is driven by a destructive supply shock, margins contract, and yields rise because inflation risk rather than productive growth is being repriced. The observable prices may look similar while the underlying regime is opposite. We therefore refused to label every increase in yields as bearish or every increase in oil as inflationary. We asked what caused the move, how persistent it was, and where financing stress would appear first.
本月的市場思考集中在成長品質的不確定性。油價、債券殖利率與股票可以同時上升,只要油價反映需求改善,企業獲利上修足以吸收貼現率提高。同樣的三種價格變化,如果源自破壞性的供給衝擊、利潤率受壓,以及市場因通膨風險而非生產性成長重新定價,意義便完全相反。表面的價格方向可能相似,底層市場狀態卻可能相反。因此,我們不把每一次殖利率上升都直接視為利空,也不把每一次油價上升都簡化為通膨交易。我們更重視變動的原因、持續時間,以及融資壓力會首先在哪個環節出現。
Our trading action was deliberately small. We reduced reliance on long-duration assets as a universal hedge, maintained yield-oriented exposures with short repricing horizons, and reserved risk capacity for a cleaner transition from high-noise price discovery to a tradable regime. We did not add exposure merely because prices fell. Lower prices are not the same as better odds. We required stabilization in volatility, evidence that funding conditions were not deteriorating, and confirmation that correlations were returning to a structure in which diversification could be trusted.
我們的交易行動刻意保持小規模。我們降低把長久期資產當作萬用避險工具的依賴,保留重新定價週期較短的收益型曝險,並為市場從高雜訊價格發現轉向可交易狀態預留風險容量。我們不會只因價格下跌就增加曝險。價格較低不代表勝率較高。我們需要看到波動結構穩定、融資條件沒有惡化,並確認資產相關性回到可以信任分散效果的狀態。
The position for the year currently records a profit of +0.00005 unit, before any interpretation beyond the accounting result. The number is economically immaterial, but operationally useful. It shows that the portfolio survived the observation period without paying a large tuition fee for an unverified view. We do not present this result as skill, statistical significance, or a repeatable return. At this scale, transaction costs, valuation conventions, and timing can dominate the outcome. The professional response is not celebration. It is measurement discipline.
本年度目前部位錄得正收益 +0.00005 單位。在會計結果以外,我們不作過度解讀。這個數字在經濟上沒有重大意義,但在操作上仍有價值,因為它顯示投資組合在觀察期間內存活下來,沒有為尚未驗證的觀點支付高昂學費。我們不把它包裝成技巧、統計顯著性或可重複回報。在如此微小的尺度下,交易成本、估值慣例與執行時點都可能主導結果。專業的反應不是慶祝,而是維持測量紀律。
The lesson learned is that a hedge must be tested under the same liquidity conditions in which it is expected to work. Historical negative correlation is not protection if both assets are sold to meet margin calls. We also learned that waiting is an active allocation decision when the distribution of outcomes is wide and the information advantage is narrow.
本期教訓是,避險必須在它真正需要發揮作用的流動性條件下接受檢驗。如果兩項資產都因保證金需求而被迫出售,歷史上的負相關並不等於保護。我們也再次確認,當結果分布很寬、資訊優勢很窄時,等待本身就是主動的資產配置決策。
The practical value of risk-path compression is that it connects observable market data to a governed portfolio response. Energy prices alone are not an instruction. We examine whether the move is spot-led or curve-led, whether inflation breakevens confirm it, whether real yields are rising, whether rate volatility is increasing, and whether funding spreads are beginning to reflect balance-sheet scarcity. A shock becomes actionable only when several links persist in sequence. This reduces the probability of reacting to a one-day headline while remaining sensitive to a genuine regime change.
風險路徑壓縮的實務價值,在於把可觀察的市場資料連接到受治理的投資組合反應。能源價格本身不是交易指令。我們會檢查變動是由現貨還是期限曲線主導、通膨損益平衡點是否確認、實質殖利率是否上升、利率波動是否增加,以及融資利差是否開始反映資產負債表稀缺。只有當多個環節依序且持續得到確認,衝擊才具有可執行意義。這能降低我們對單日新聞過度反應的機率,同時保持對真正市場狀態轉換的敏感度。
Portfolio governance converts this chain into ownership and timing. Each monitored variable has a responsible reviewer, a normal range, a stress range, an escalation condition, and a required decision record. The purpose is not bureaucratic complexity. It is to prevent a portfolio from remaining unchanged simply because no individual person is explicitly responsible for declaring that the original assumption has failed.
投資組合治理把這條傳導鏈轉化為明確的責任與時點。每個監控變數都有負責檢視者、正常區間、壓力區間、升級條件與必要決策紀錄。這並非追求官僚式複雜,而是避免原始假設已失效,投資組合卻因沒有人被明確指定負責宣告失效而維持不變。
A transmission chain is useful only when it distinguishes a temporary price impulse from a durable change in financial conditions. We therefore compare level, direction, persistence, and breadth. A rise in oil accompanied by stable inflation expectations and orderly credit may remain a sector event. The same rise accompanied by higher breakevens, a steeper inflation-risk premium, wider funding spreads, and falling market depth is more likely to become a portfolio event. This distinction determines whether we observe, hedge, or reduce gross risk.
傳導鏈只有在能區分暫時價格脈衝與金融條件持久改變時才有用。因此,我們同時比較水準、方向、持續性與廣度。若油價上升,但通膨預期穩定、信用市場秩序正常,它可能仍只是產業事件。若同一油價上升同時伴隨損益平衡通膨率提高、通膨風險溢價變陡、融資利差擴大與市場深度下降,它就更可能成為投資組合事件。這項區分決定我們應繼續觀察、建立避險,還是降低總風險。
Capital preservation does not mean eliminating volatility. A portfolio with no visible fluctuation may still contain concentrated credit, stale pricing, or liquidity risk. Our objective is to avoid losses that impair the portfolio's ability to recover. We therefore focus on drawdown depth, drawdown duration, financing resilience, and the amount of risk capacity remaining after a shock. Temporary mark-to-market loss can be acceptable when the thesis, liquidity, and funding remain intact. A smaller loss can be unacceptable when it reveals a broken control or an unbounded exposure.
資本保全不代表消除波動。表面上沒有明顯波動的投資組合,仍可能包含集中信用、陳舊定價或流動性風險。我們的目標是避免損害投資組合復原能力的損失。因此,我們關注回撤深度、回撤持續時間、融資韌性,以及衝擊後仍剩餘多少風險容量。當論點、流動性與融資仍然完整時,暫時性帳面損失可以接受;但若較小損失揭露控制失效或無邊界曝險,它仍不可接受。
Our operating discipline is to separate alert, escalation, and action thresholds. An alert increases monitoring. Escalation requires cross-checking by more than one risk carrier. Action changes capital. This hierarchy prevents every unusual market print from triggering turnover while ensuring that a confirmed propagation pattern receives a timely portfolio response.
我們的操作紀律會區分警示、升級與行動閾值。警示代表提高監控頻率;升級要求由一種以上的風險載體交叉確認;行動則真正改變資本配置。這個層級能避免每個異常市場報價都觸發交易周轉,同時確保已確認的擴散模式能及時得到投資組合回應。
Our next action is to strengthen three controls while establishing a decision clock. First, every proposed hedge must pass a normal, weakened, and crisis-correlation test. Second, every risk addition must identify the intermediary variable that would invalidate it. Third, every position must have a prewritten reduction rule that applies regardless of whether the position is profitable. Fast variables such as volatility, funding, and market depth will be reviewed more frequently than slow variables such as fiscal structure or capital-expenditure cycles. We will not force all evidence into the same horizon. A sound macro process distinguishes what can change by the hour, what changes by the quarter, and what should alter the strategic portfolio only after repeated confirmation. We will continue to optimize for a stable return path under a visible drawdown budget, not for the appearance of constant activity.
下一步,我們會在建立決策時鐘的同時強化三項控制。第一,每一項避險都要通過正常、減弱與危機三種相關性狀態的測試。第二,每一次新增風險都要明確指出會使投資理由失效的中介變數。第三,每一個部位都要預先寫下減曝規則,而且不論當時盈虧都必須適用。波動、融資與市場深度等快速變數,會比財政結構或資本支出週期等慢速變數更頻繁地接受檢視。我們不會強迫所有證據使用相同時間尺度。穩健的宏觀流程必須區分哪些因素可能每小時改變、哪些因素按季改變,以及哪些因素只有在反覆確認後才應改變策略投資組合。我們將繼續在清楚可見的回撤預算下,追求較穩定的收益路徑,而不是追求持續交易的表象。