Small Profit, Large Information
第 5 封:小利潤,大資訊
Dear Shareholders,
致股東:
This letter addresses the smallest number in our reporting and the largest temptation in investment communication: the temptation to make a result sound more meaningful than it is.
本封信討論報告中最小的數字,以及投資溝通中最大的誘惑:把一項結果說得比實際上更有意義。
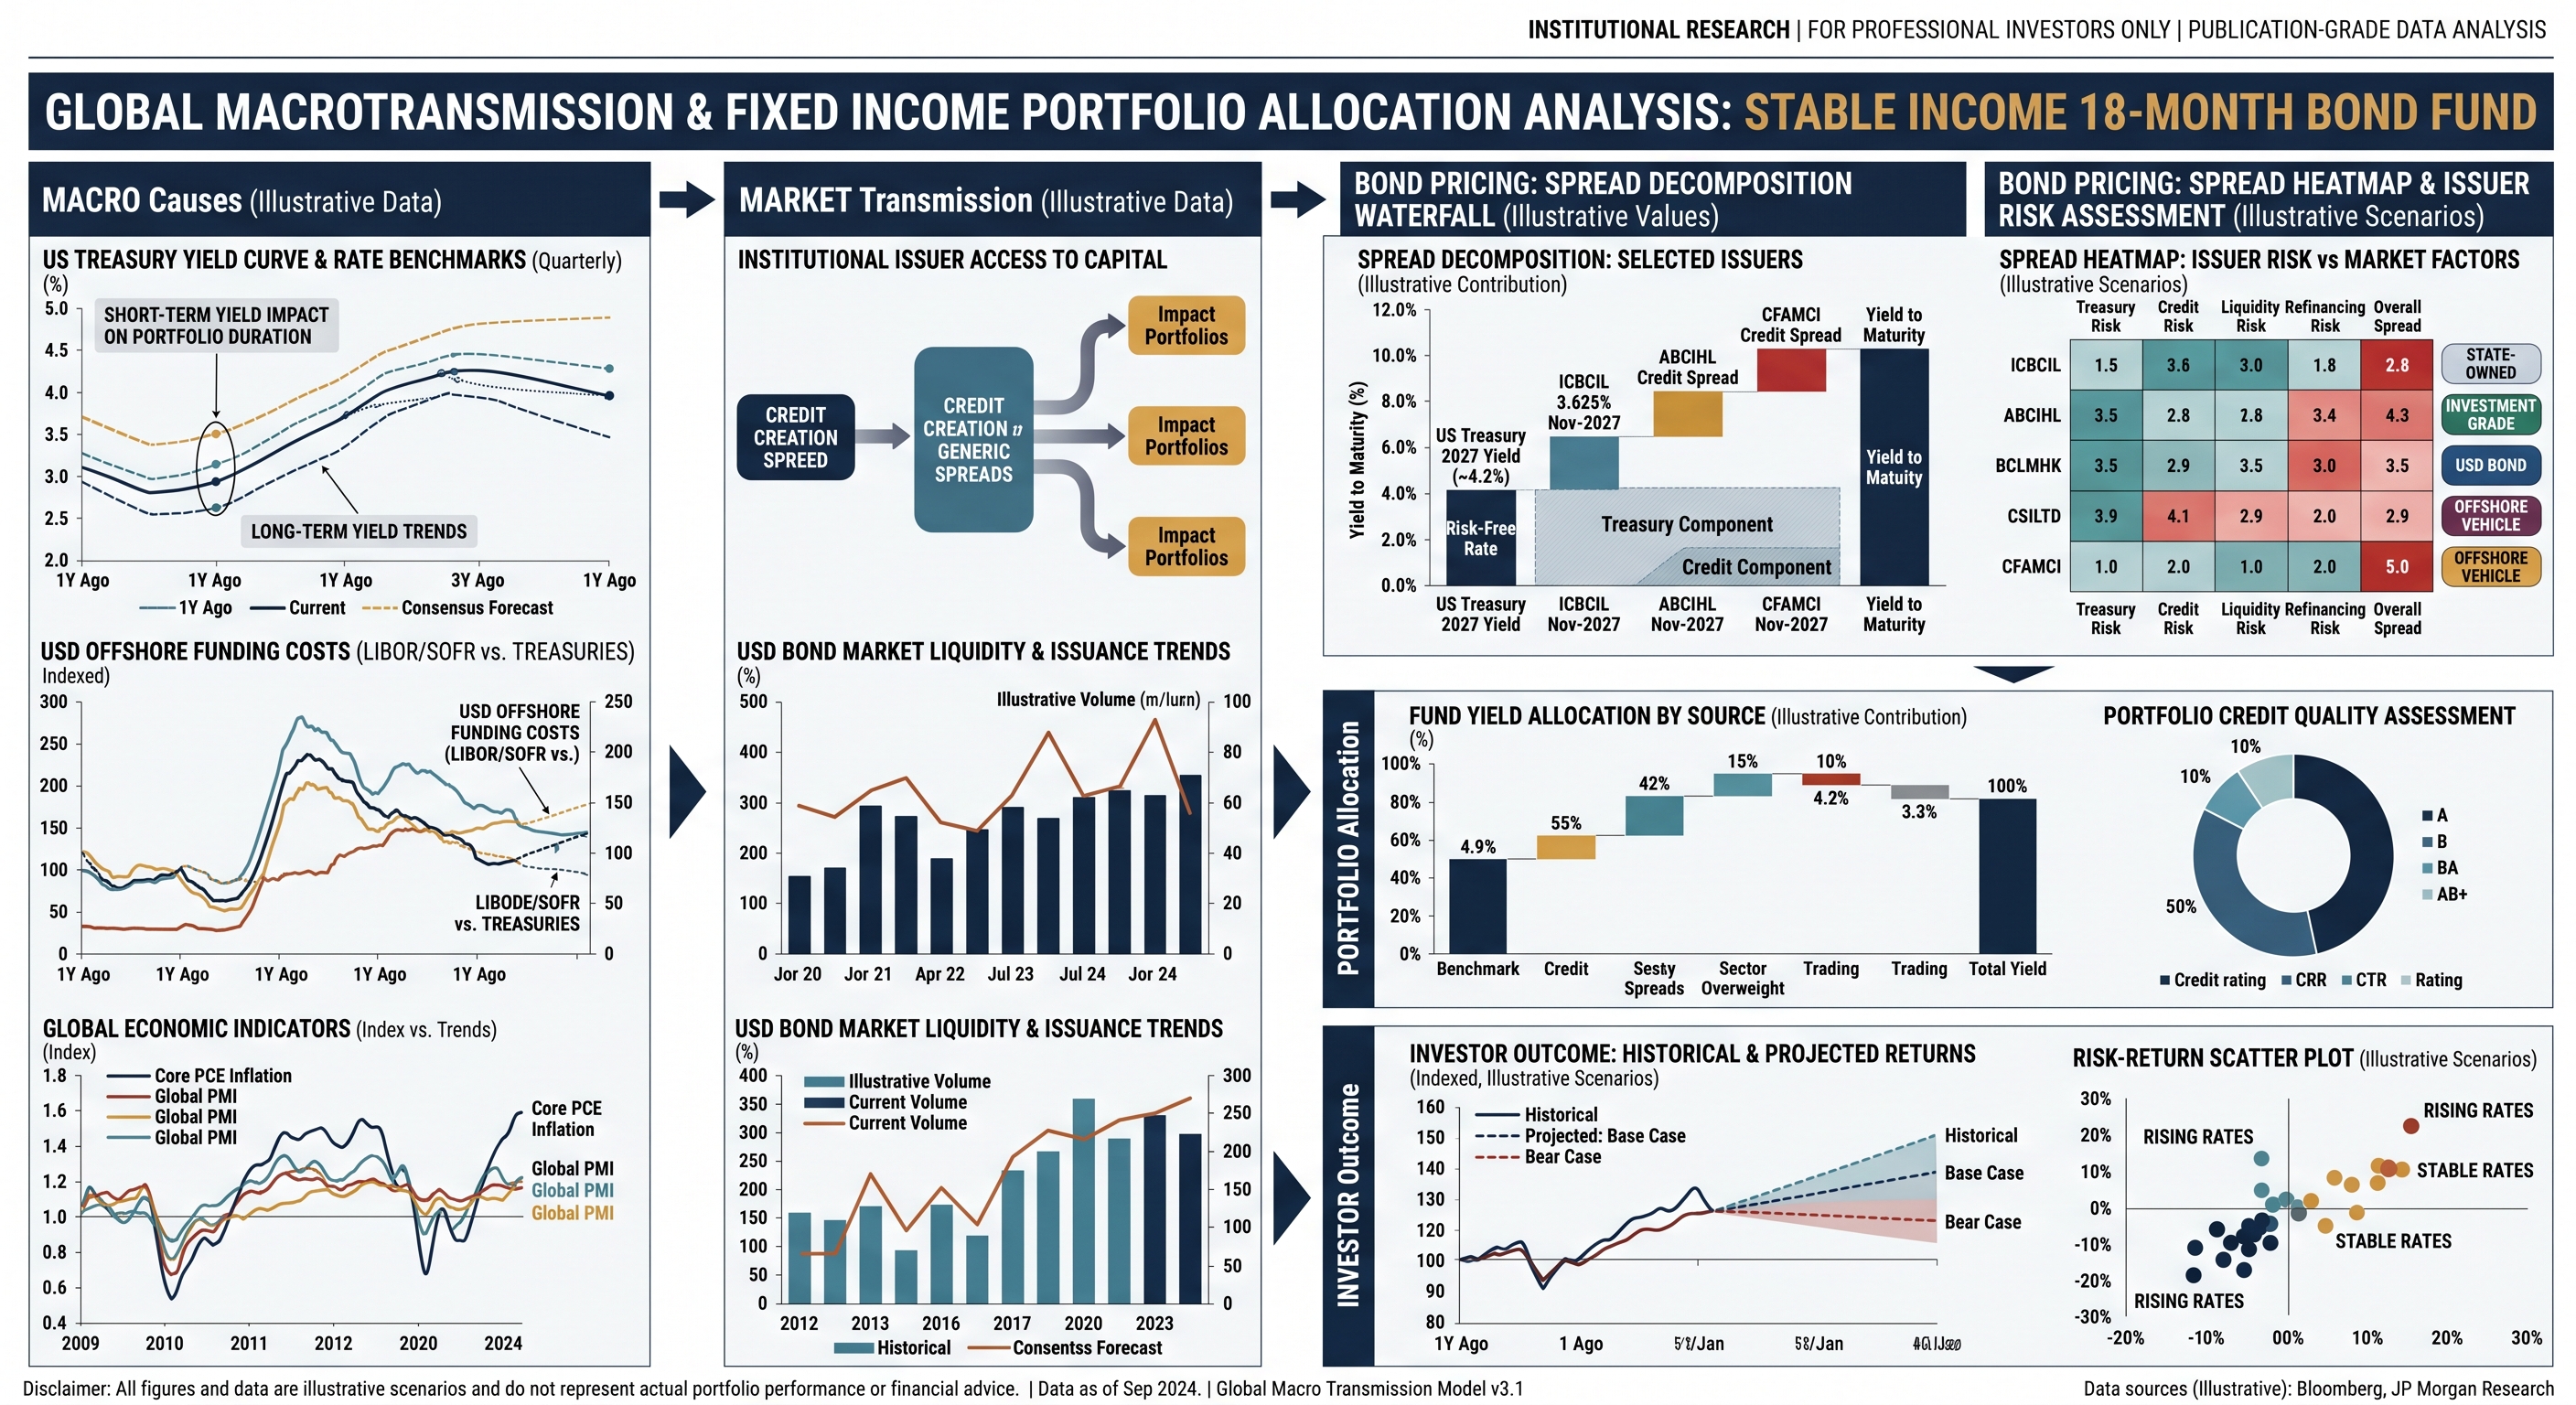
The position for this year is +0.00005 unit profit. We report it because accurate records matter. We do not celebrate it because economic materiality matters too. A result can be positive and still contain almost no evidence about skill. It can also be small while revealing meaningful information about execution, costs, and risk control. Our responsibility is to separate the accounting fact from the causal claim.
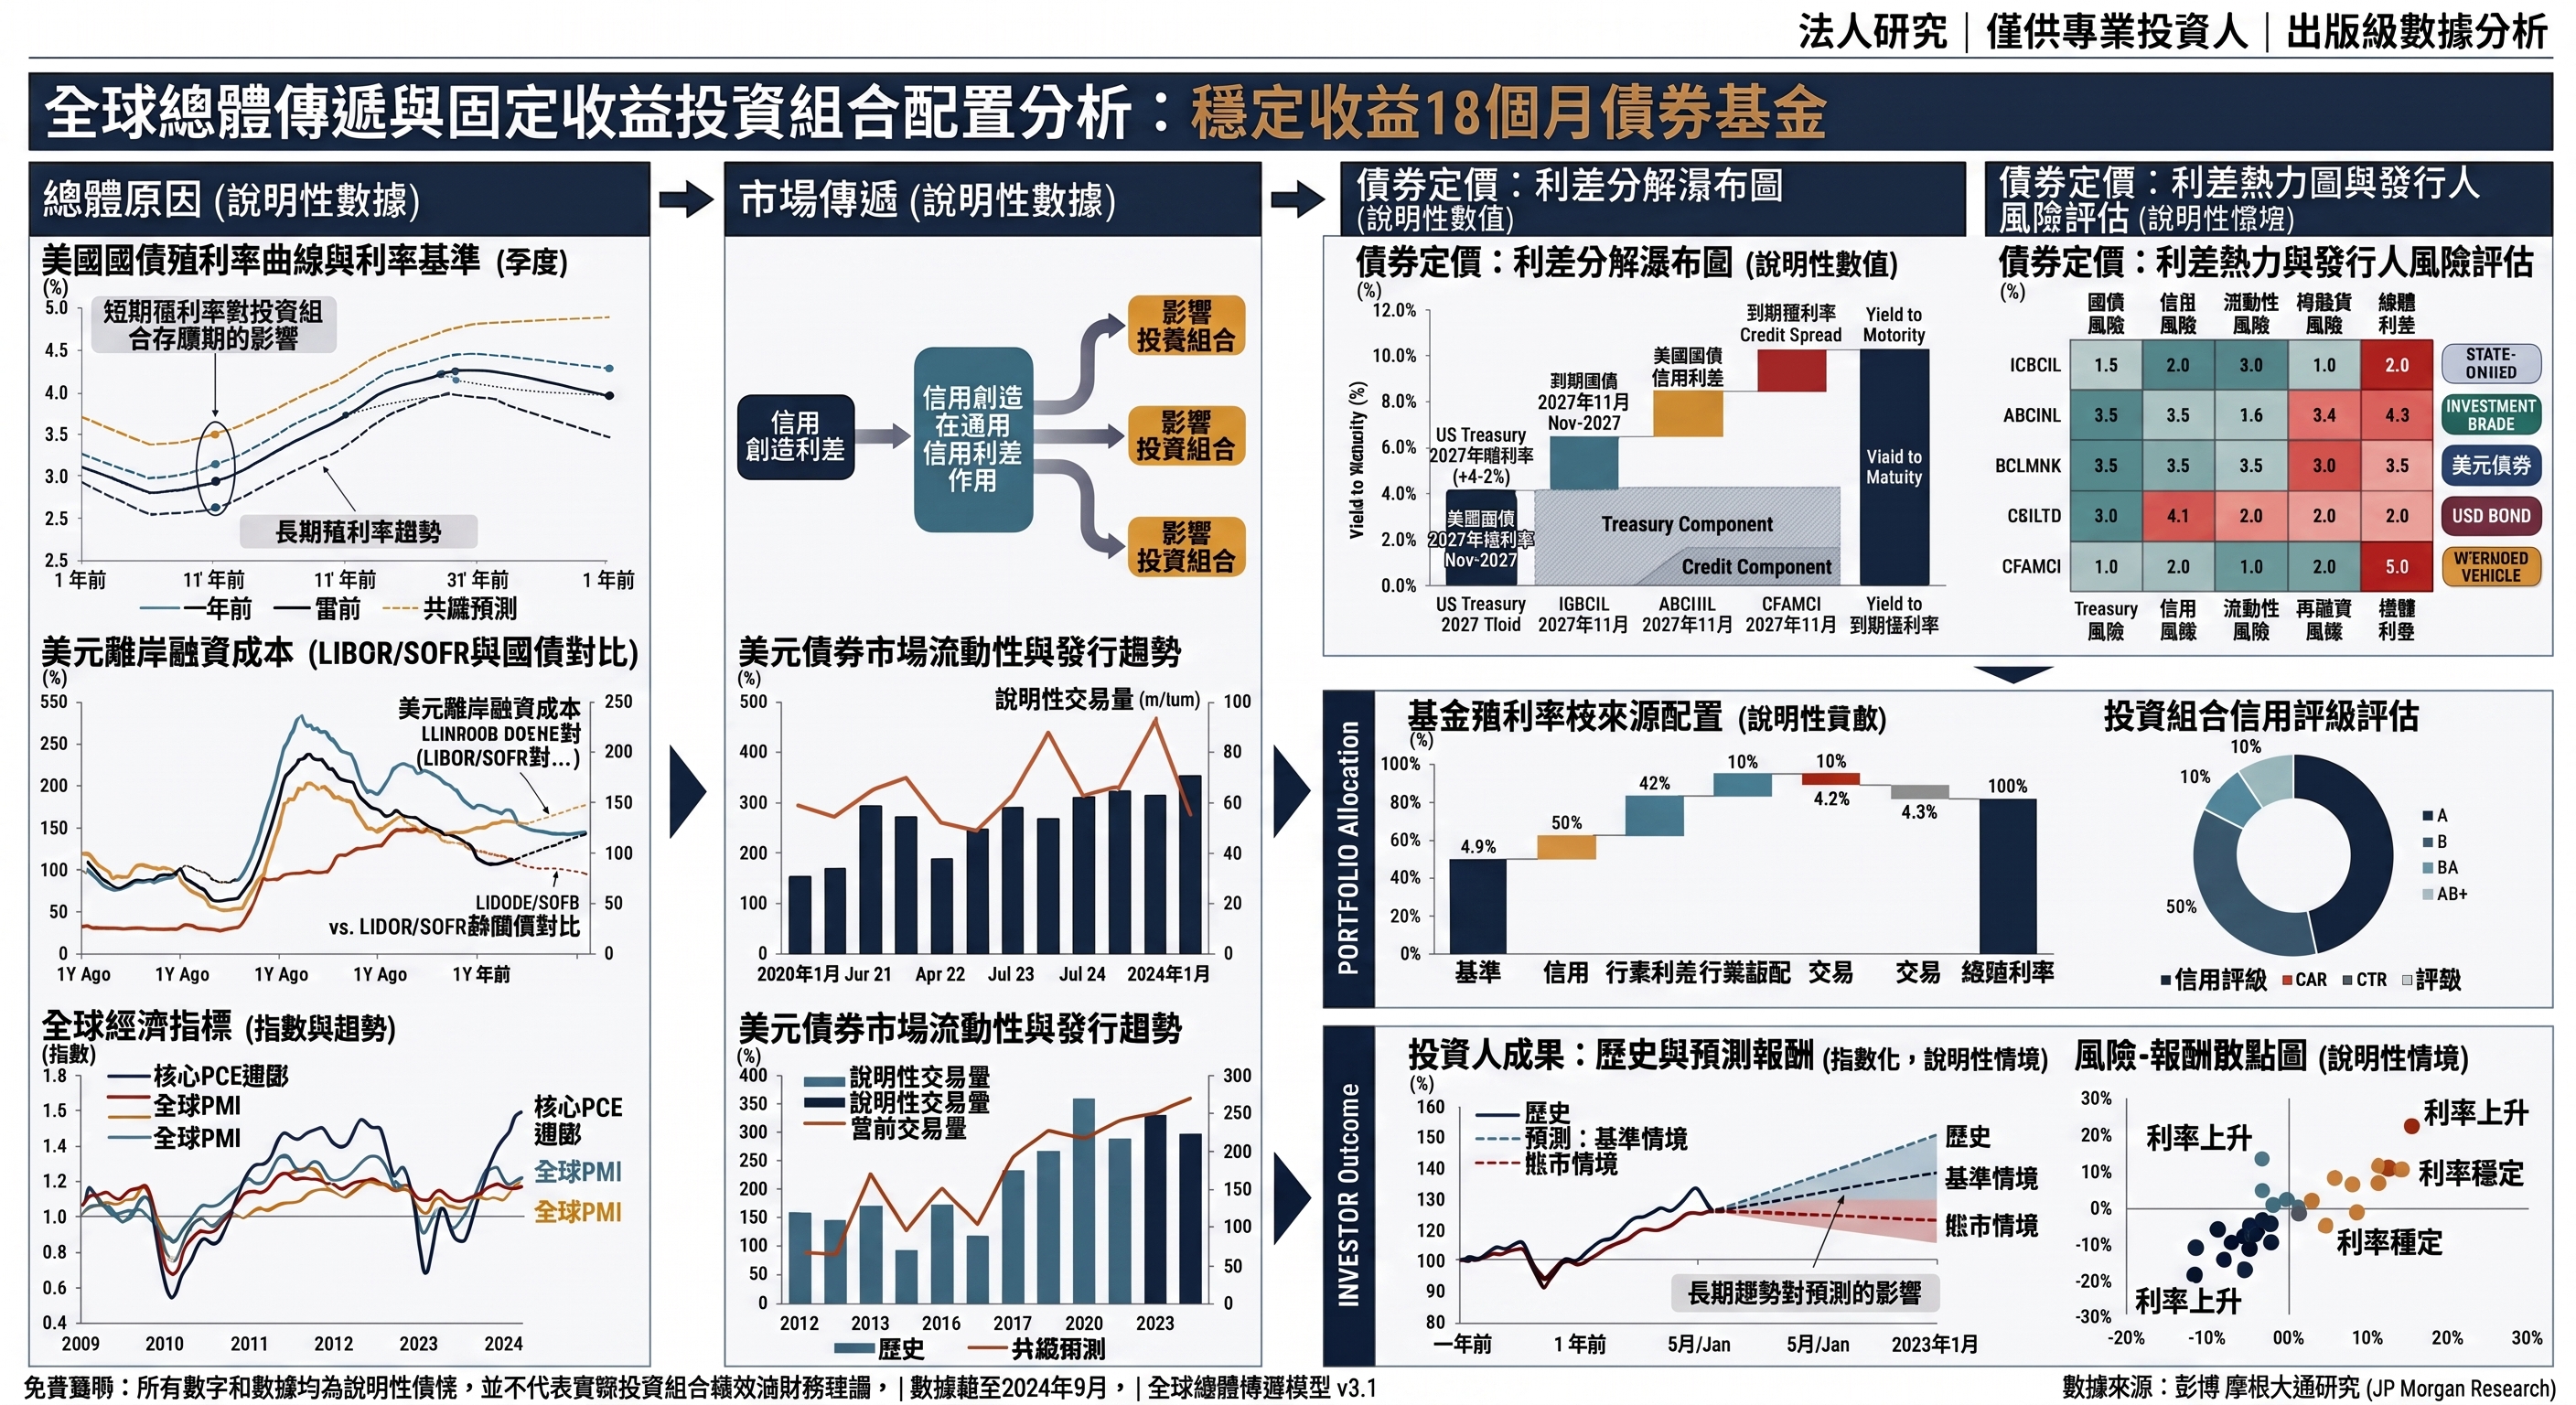
本年度部位為 +0.00005 單位正收益。我們揭露它,是因為準確紀錄很重要。我們不慶祝它,是因為經濟重大性同樣重要。一個結果可以是正數,卻幾乎沒有提供任何關於技巧的證據。它也可以非常微小,卻揭露了執行、成本與風險控制的重要資訊。我們的責任,是把會計事實與因果主張分開。
Our trading framework reviews P&L through attribution rather than headline direction. We ask how much came from beta, carry, roll-down, curve movement, spread movement, currency, convexity, security selection, financing, and residual effects. We then compare realized behavior with the pre-trade expectation. If the portfolio earned a tiny amount while using very little risk, the result may be consistent with design. If it earned the same amount after taking large hidden tail risk, the process is unacceptable even though the sign is positive.
我們的交易框架透過損益歸因,而不是只看正負方向,進行檢討。我們詢問有多少結果來自市場 beta、票息、曲線滾降、殖利率曲線變動、信用利差變動、貨幣、凸性、證券選擇、融資與殘差。接著,我們把實際行為與交易前預期比較。如果投資組合用極低風險賺取微小收益,結果可能符合設計。如果同樣收益來自龐大且隱藏的尾端風險,即使結果為正,流程仍不可接受。
Our market thinking was that uncertainty should lower position size before it lowers intellectual conviction. We may have a strong long-term belief about fiscal expansion, AI infrastructure, supply constraints, or inflation volatility, but long-term truth does not remove short-term path risk. Markets can move through several regimes before reaching an eventual destination. We therefore avoided converting thematic confidence into leverage without a visible update rule.
本期市場思考是,不確定性應先降低部位,而不一定要先降低長期觀點的信念。我們可能對財政擴張、AI 基礎設施、供給約束或通膨波動具有強烈長期判斷,但長期正確不會消除短期路徑風險。市場可能在抵達最終方向之前經歷數個不同狀態。因此,在沒有清楚更新規則時,我們不會把主題信心直接轉化為槓桿。
Our trading action centered on measurement hygiene. We separated realized from unrealized P&L, market movement from cash flow, gross return from net return, and model price from executable price. We resisted annualizing a short observation period. We also documented decisions that produced no trade, because avoided losses and missed gains must be reviewed symmetrically.
交易行動集中於測量衛生。我們區分已實現與未實現損益、市場價格變化與現金流、毛報酬與淨報酬,以及模型價格與真正可成交價格。我們拒絕把短期觀察值年化。我們也記錄最後沒有執行的決策,因為避免的損失與錯過的收益必須對稱檢討。
The lesson learned is that P&L is an output, not a complete diagnosis. Positive P&L can hide poor process, and negative P&L can occur under a sound process when a low-probability event arrives. That does not mean outcomes are irrelevant. A process that repeatedly loses must be changed. It means that one observation should update confidence in proportion to its statistical and economic information content.
本期教訓是,損益是輸出,不是完整診斷。正損益可能掩蓋不良流程;當低機率事件發生時,負損益也可能出現在合理流程之下。這不代表結果不重要。持續虧損的流程必須改變。真正意思是,單一觀察應依照其統計與經濟資訊含量,按比例更新我們的信心。
The +0.00005 unit profit should be read as a reporting datum, not a performance ratio. Without a defined capital base, currency, fee convention, valuation timestamp, and benchmark, it cannot support comparisons. Even after those definitions are supplied, a very small result may be dominated by rounding, accrued income, bid-versus-mid valuation, or a single execution. We preserve the number for audit continuity while refusing to attach unsupported economic meaning to it.
+0.00005 單位正收益應被視為一項報告資料,而不是績效比率。在未定義資本基礎、計價貨幣、費用慣例、估值時點與比較基準之前,它不能用於比較。即使補充這些定義,極小結果仍可能主要由四捨五入、應計收入、買價與中間價估值差異,或單一執行所主導。我們為了稽核連續性保留該數字,同時拒絕賦予缺乏支持的經濟意義。
A fuller performance review links return with risk consumed. We consider gross and net exposure, realized and implied volatility, maximum adverse excursion, drawdown duration, downside deviation, concentration, liquidity usage, and the stability of return attribution. Sharpe and Sortino measures can be informative once the observation set is sufficient, but neither should be treated as reliable when the sample is short or returns are non-normal.
更完整的績效檢討會把回報與消耗的風險連接起來。我們考慮總曝險與淨曝險、已實現與隱含波動、最大不利變動、回撤持續時間、下行偏差、集中度、流動性使用,以及回報歸因的穩定性。當觀察樣本足夠時,Sharpe 與 Sortino 指標可以提供資訊;但當樣本過短或報酬分布不是常態時,兩者都不應被視為可靠結論。
Performance attribution must reconcile from security-level P&L to the portfolio total. Unexplained residuals are investigated rather than absorbed into a miscellaneous category. Common sources include accrued interest, foreign-exchange translation, stale prices, corporate actions, financing allocations, and differences between trade-date and settlement-date accounting. Reliable attribution is a control system, not merely a presentation tool.
績效歸因必須能從證券層級損益核對至投資組合總額。無法解釋的殘差應接受調查,而不是被吸收到雜項類別。常見來源包括應計利息、外匯換算、陳舊價格、公司行動、融資分配,以及交易日與交割日會計差異。可靠歸因是一套控制系統,不只是簡報工具。
Benchmark selection must reflect the mandate. A short-duration income strategy should not be judged only against a long-duration credit index, because the comparison can reward or punish duration rather than security selection. We may use several references: cash or short government instruments for opportunity cost, a maturity-matched credit universe for selection quality, and a broad market index for context. None becomes a substitute for the strategy's absolute drawdown objective.
基準選擇必須反映任務。短久期收益策略不應只與長久期信用指數比較,因為比較結果可能獎勵或懲罰久期,而不是證券選擇。我們可能同時使用多種參考:現金或短期政府工具衡量機會成本、期限匹配的信用集合衡量選券品質,以及廣泛市場指數提供背景。但任何一項都不能取代策略本身的絕對回撤目標。
Shareholder communication will distinguish fact, estimate, scenario, and judgment. Facts are recorded without embellishment. Estimates include methods and limitations. Scenarios describe conditional paths rather than forecasts. Judgments explain why capital was or was not committed. This discipline is particularly important for the +0.00005 unit result, which remains an exact record but not a basis for promotional interpretation.
股東溝通會區分事實、估計、情境與判斷。事實按原貌記錄,不加修飾;估計附上方法與限制;情境描述有條件的路徑,而不是預測;判斷則說明資本為何投入或沒有投入。這項紀律對 +0.00005 單位結果尤其重要,因為它仍是一項精確紀錄,但不是宣傳式解讀的基礎。
Our next action is to publish a compact attribution alongside future letters and apply an evidence hierarchy to every performance claim. The attribution will show the source of return, risk used, largest adverse path, liquidity consumed, and deviations from plan. Audited and independently valued results will rank above internal estimates; realized results above hypothetical scenarios; long samples above short samples; and net results above gross illustrations. We will not use a tiny positive result to claim victory. We will use it to improve the machinery that must eventually produce results of genuine economic significance, while the evidence hierarchy protects shareholder communication from accidental exaggeration.
下一步,我們將在未來股東信中附上精簡歸因,並為每項績效主張採用證據層級。歸因會說明回報來源、使用的風險、最大不利路徑、消耗的流動性,以及與原計畫的偏離。經稽核及獨立估值結果高於內部估計,已實現結果高於假設情境,長期樣本高於短期樣本,淨結果高於毛額示意。我們不會用微小正收益宣稱勝利,而會用它改善最終必須產生真正經濟成果的投資機器;證據層級則可防止股東溝通無意間出現誇大。